Dubai vs London: Is Property Still Good Value ?
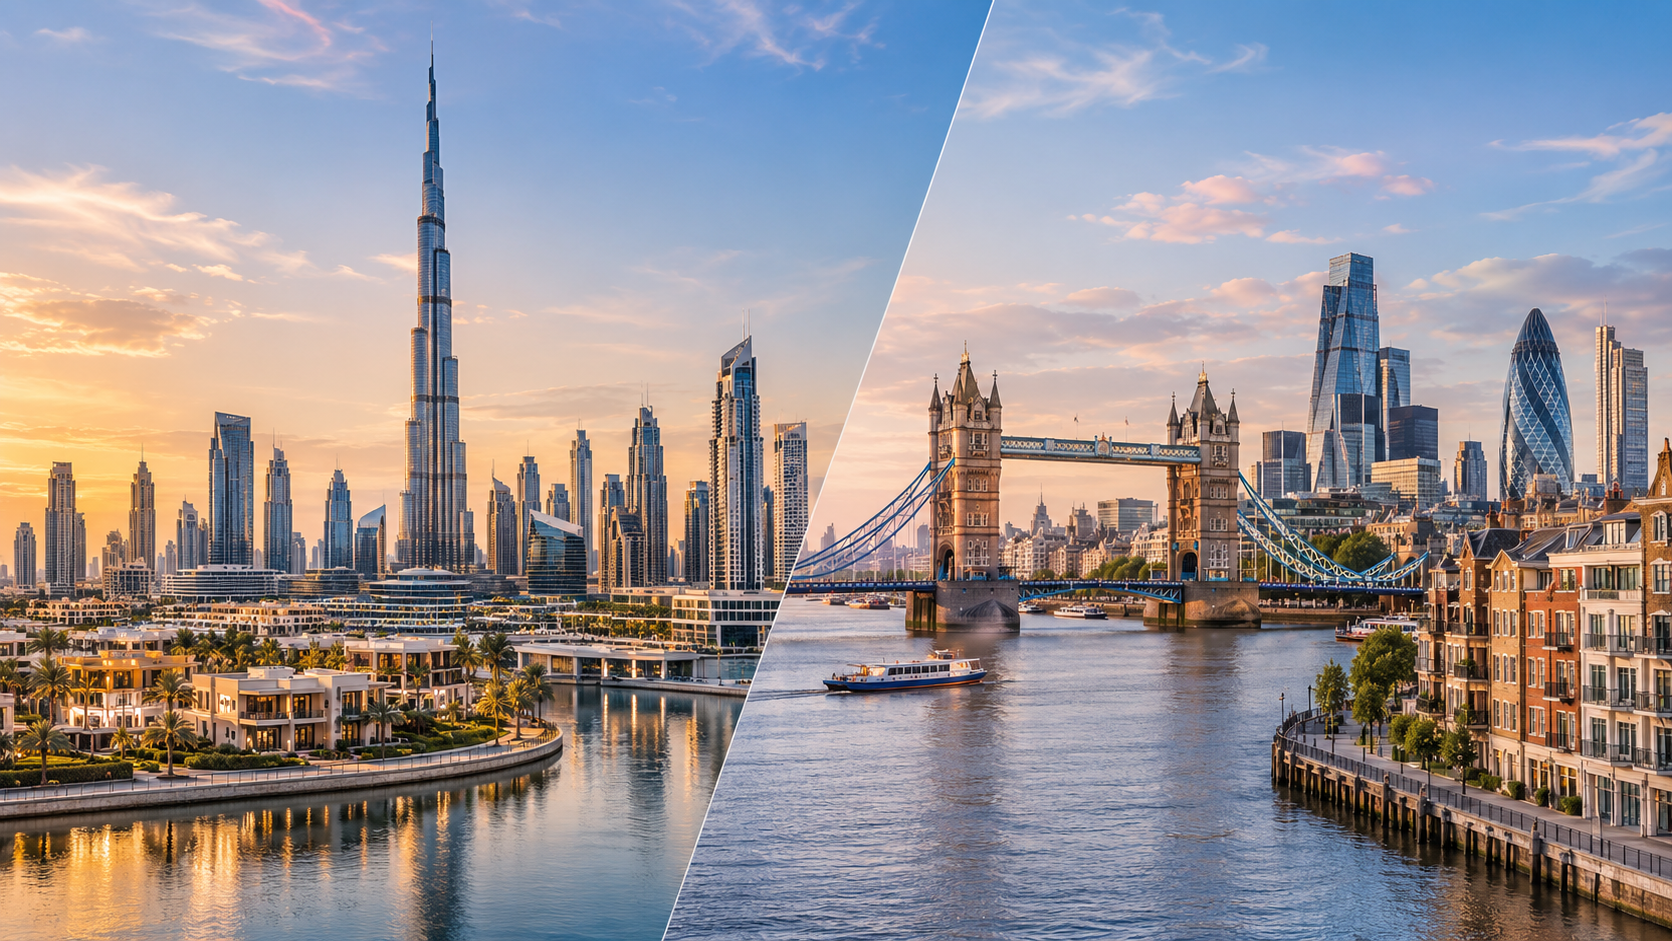
Buying property in a global city can offer long-term investment potential, but high prices do not automatically mean good value. In 2026, investors comparing Dubai vs London property investment need to look beyond headline prices and consider rental income, buying costs, taxation, market conditions, and the risks associated with each location.
Dubai continues to attract international buyers with its modern residential communities, established rental market, and range of off-plan and ready properties. London offers a mature property market with established neighbourhoods, global economic connections, and long-term housing demand. However, both markets face different challenges, and neither guarantees capital appreciation.
So, is property still good value in 2026? The answer depends on the investor’s budget, income objectives, investment period, and tolerance for risk.
Dubai vs London Property Investment: Quick Comparison
| Factor | Dubai | London |
|---|---|---|
| Property market | Dynamic market with ready and off-plan options | Mature market with established and new-build properties |
| Rental income | Attractive gross yields in many residential areas | Rental demand, but high purchase prices can affect yields |
| Buying costs | Includes Dubai Land Department registration and other transaction costs | Includes Stamp Duty Land Tax (SDLT), legal fees, and other costs |
| Tax considerations | Different personal and corporate tax framework | UK property tax rules can affect rental income and ownership costs |
| Capital growth | Varies by community, supply, and market cycle | Varies by borough, property type, and wider economic conditions |
| Main risks | New supply, price cycles, service charges, and off-plan delivery | High entry costs, financing costs, taxation, and local price movements |
| Potential fit | Investors prioritising rental income and international property exposure | Investors seeking exposure to an established UK market |
This comparison is a starting point rather than a guarantee of performance. The figures and costs for a specific property can differ substantially from citywide averages.
1. Are Dubai Property Prices Still Attractive in 2026?
Dubai offers a broad range of residential properties, from apartments in established urban communities to waterfront residences, family villas, and off-plan developments. This variety allows buyers to compare different entry prices, rental strategies, and holding periods.
According to Engel & Völkers’ H1 2026 Dubai Residential Property Market Report, Dubai recorded 80,509 residential property sales worth AED 226.5 billion during the first half of 2026. The report also recorded an average gross residential rental yield of 6.6% in June 2026.
These figures show an active market, but high transaction volumes do not mean every property is fairly priced. Investors should examine comparable completed sales, current rents, service charges, nearby competing developments, and the amount of new supply expected in the area.
Dubai areas worth comparing
- Jumeirah Village Circle (JVC): A broad residential market with apartments and family-oriented housing options.
- Dubai Marina: An established waterfront location that attracts residents seeking access to leisure facilities and transport links.
- Business Bay: A central business and residential district with apartments aimed at professionals and urban residents.
- Dubai Hills Estate: A master-planned community offering apartments, villas, green spaces, and family amenities.
- Dubai South: A developing district where investors should assess infrastructure progress, future supply, and the timing of expected demand.
Each area has a different price level, tenant profile, and supply pipeline. A lower purchase price may provide a more accessible entry point, but it does not necessarily mean better value if rental demand or resale liquidity is weaker.
2. Is London Property Becoming Better Value?
London remains one of the world’s major business, financial, educational, and cultural centres. Its property market is well established, but prices vary significantly between boroughs and property types.
According to the UK House Price Index for August 2026, the average London property price was approximately £554,000, down 2.2% compared with August 2025. The average price of flats in London fell by 5.0% over the same period.
This decline may create opportunities for buyers who can negotiate carefully, particularly where sellers are adjusting expectations. However, a fall in average prices is not proof that every property is undervalued. Investors must consider the building’s condition, service charges, local rental demand, transport access, and likely resale market.
London locations to compare
- Canary Wharf: A business district with residential properties serving professionals and people seeking access to major employment centres.
- Stratford: A regeneration-focused area with transport connections, retail facilities, and a mix of residential developments.
- Barking and Dagenham: An area that may offer a lower entry price than many inner London locations, depending on property type.
- Greenwich: A residential market combining established neighbourhoods, transport links, and lifestyle attractions.
- Westminster: A central location with premium properties and a substantially higher price point than many outer boroughs.
The right comparison is between similar properties serving similar tenants, not simply between the average price in Dubai and the average price in London.
3. Rental Yields: Which Market Offers Better Income Potential?
Rental yield is one of the most important measures for an income-focused investor. It shows the annual rental income as a percentage of the property’s purchase price.
Dubai’s H1 2026 market report from Engel & Völkers recorded an average gross residential rental yield of 6.6% in June 2026. The report gave average yields of 6.9% for apartments, 5.1% for townhouses, and 4.5% for villas. Actual performance varies by location and individual property.
London can offer strong rental demand, but its high purchase prices can make it harder for some properties to generate a high gross yield. Investors should calculate the expected yield using realistic achievable rent and the full purchase price, rather than relying on advertised rents or broad market averages.
How to calculate rental yield
Gross rental yield formula:
Annual rent ÷ Property purchase price × 100
For example, if a property costs AED 1,000,000 and generates AED 65,000 in annual rent:
AED 65,000 ÷ AED 1,000,000 × 100 = 6.5% gross rental yield.
This is an illustrative calculation, not a forecast for a particular property.
Gross yield does not account for service charges, maintenance, insurance, management fees, periods without a tenant, financing, or taxes. Net yield is therefore more useful when comparing the actual income expected from two investments.
For a fair Dubai-versus-London comparison, calculate the same measures for each property:
- Total purchase and transaction costs
- Realistic annual rental income
- Expected vacancy and maintenance expenses
- Management and service charges
- Financing costs and applicable taxes
- Net annual income after recurring expenses
A property with a higher advertised yield may not deliver the better return after expenses.
4. Buying Costs and Taxes: What Should Investors Budget For?
The purchase price is only part of the cost of buying property. Transaction fees and tax rules can materially affect the return, especially for investors purchasing from overseas.
Buying property in Dubai
The Dubai Land Department’s property sale registration guidance lists a 2% fee for the buyer and a 2% fee for the seller under its stated registration process, alongside additional registration and service-partner fees. The allocation of fees can depend on the transaction and agreement, so buyers should confirm the actual amount payable before signing.
Investors should also budget for any applicable agency fees, mortgage-related charges, service charges, maintenance, and property management. For off-plan properties, the payment schedule and any applicable registration or administrative charges should be checked against the sale and purchase agreement.
Buying property in London
Buyers in England may need to pay Stamp Duty Land Tax (SDLT), depending on the purchase price and their circumstances. The amount varies according to the property’s value, whether it is an additional property, and whether the buyer qualifies as a UK resident for SDLT purposes.
The UK government applies a 2-percentage-point SDLT surcharge to qualifying purchases by non-UK residents in England and Northern Ireland. Higher rates can also apply to additional residential properties. Review the current HMRC guidance on the non-UK resident SDLT surcharge before calculating your budget.
London investors should also account for legal fees, survey costs, mortgage fees where relevant, ongoing maintenance, insurance, and property management.
Important: Tax treatment depends on personal circumstances, ownership structure, and tax residency. Investors should obtain professional tax advice before making a purchase.
5. Capital Appreciation: Where Could Property Values Grow?
Capital appreciation is the increase in a property’s value over time. It can contribute significantly to investment returns, but it is less predictable than rental income and should not be treated as guaranteed.
Dubai’s growth factors
Dubai’s property market is influenced by population and employment trends, international investment, tourism, infrastructure, new residential supply, and buyer confidence. New communities can benefit from improving infrastructure and services, but large development pipelines can also create competition between similar properties.
Off-plan purchases may offer staged payments and access to new developments, but investors need to assess construction progress, the developer’s delivery record, contractual terms, and the resale conditions that apply before handover.
London’s growth factors
London’s property values are influenced by employment, mortgage affordability, interest rates, housing supply, transport improvements, and demand across individual boroughs. Established locations may benefit from long-term demand, but high prices can limit affordability and short-term price growth.
The August 2026 UK House Price Index shows that London prices declined year-on-year, with flats experiencing a larger fall than the overall market. This highlights the importance of examining property types and local conditions rather than assuming that all London property appreciates steadily.
For both cities, a sound investment decision should work under conservative assumptions rather than depending on rapid future price growth.
6. Currency, Financing, and International Investor Considerations
International investors should consider currency exposure as well as the property itself.
Dubai property is generally priced in UAE dirhams, which is pegged to the US dollar. London property is priced in pounds sterling. For an investor whose income or savings are held in another currency, exchange-rate movements can affect the final cost of buying, the value of rental income when converted, and the return received when selling.
Financing is another key difference. Mortgage eligibility, deposit requirements, interest rates, and lending criteria vary according to the buyer’s residency, income, nationality, and financial position.
Before investing, compare the total cost of borrowing and consider how the investment would perform if interest rates increased, rents were lower than expected, or the property remained vacant for longer than planned.
7. What Are the Main Risks in 2026?
Neither Dubai nor London is risk-free. Investors should understand the risks that matter most to their chosen property.
Dubai risks include:
- Additional supply in areas with many competing developments
- Price volatility during changes in market sentiment
- Delays or contractual risks associated with off-plan projects
- Service charges, vacancy, and maintenance reducing net returns
- Resale restrictions or limited buyer demand for a specific property
London risks include:
- High acquisition costs and tax liabilities
- Mortgage affordability and financing costs
- Changes in rental regulation and landlord obligations
- High service charges or major works in apartment buildings
- Localised price weakness and slower resale periods
A careful due-diligence process should include checking ownership documents, the building or developer, comparable transactions, realistic rental evidence, service charges, and all applicable legal and tax obligations.
8. Dubai vs London: Which Market Suits Your Investment Goals?
There is no single answer for every investor. The more suitable market depends on what the buyer wants the property to achieve.
Dubai may suit investors who:
- Prioritise rental income and want to compare properties across different price ranges
- Prefer access to both ready homes and off-plan developments
- Want exposure to Dubai’s residential and international business market
- Are comfortable assessing new supply, development risk, and market cycles
London may suit investors who:
- Want exposure to an established UK property market
- Prefer to research specific boroughs and mature residential neighbourhoods
- Have a long investment horizon and can absorb higher entry and ownership costs
- Understand UK property taxes, landlord obligations, and financing requirements
These are general considerations, not rules. A well-priced London property can be more attractive than an overpriced Dubai property, and a carefully selected Dubai apartment can outperform a London investment with weak rental economics.
Conclusion: Is Property Still Good Value in 2026?
Dubai and London can both offer property investment opportunities in 2026, but value depends on the individual property, its total costs, and the return an investor can realistically achieve.
Dubai offers a range of residential options and recorded an average gross rental yield of 6.6% in June 2026, according to Engel & Völkers’ H1 market report. London, meanwhile, recorded an average property price of approximately £554,000 in August 2026, with prices down 2.2% year-on-year, according to the UK House Price Index. These figures describe different market measures and should not be treated as a direct performance ranking.
The strongest approach is to compare similar properties using realistic rental income, net yield, transaction costs, tax exposure, supply conditions, and the expected holding period. Instead of choosing a city based on headlines, investors should identify the property that best matches their budget and investment objectives.
At Laureate Properties, buyers can explore Dubai’s residential and off-plan opportunities and compare locations based on their individual investment criteria. Start by reviewing available off-plan property opportunities in Dubai and the communities that match your budget and preferred investment strategy.
Frequently Asked Questions
Is Dubai or London better for property investment in 2026?
Neither market is automatically better for every investor. Dubai may appeal to buyers focused on rental income and a range of new developments, while London may suit those seeking exposure to an established UK market. Compare the specific property, net yield, buying costs, taxes, and investment horizon before deciding.
Does Dubai offer higher rental yields than London?
Dubai’s H1 2026 market report from Engel & Völkers recorded an average gross residential yield of 6.6% in June 2026. London yields vary by borough and property type, so investors should compare current rental income with comparable purchase prices and recurring expenses rather than assume one city always delivers better returns.
Is London property becoming cheaper in 2026?
The UK House Price Index reported that London’s average property price was approximately £554,000 in August 2026, down 2.2% year-on-year. However, price movements differ by borough and property type, and a lower average price does not automatically mean an individual property is good value.
What costs should overseas buyers consider?
In Dubai, buyers should check property registration fees, agency fees, financing costs, and service charges. In London, buyers may need to budget for SDLT, legal fees, financing, maintenance, and management. Overseas buyers should also check any applicable tax surcharges and obtain professional tax advice.
Is off-plan property in Dubai a good investment?
Off-plan property can offer staged payment schedules and access to new developments, but it also carries construction, delivery, market, and resale risks. Review the developer’s record, contract terms, project progress, payment schedule, and competing supply before committing.
How can investors compare Dubai and London fairly?
Compare properties with similar purposes and tenant profiles. Calculate total acquisition costs, realistic annual rent, vacancy assumptions, recurring expenses, applicable taxes, financing costs, and potential resale scenarios. This gives a more useful comparison than headline prices or gross yields alone.
Disclaimer: This article is for general information only and does not constitute financial, legal, or tax advice. Market data reflects the cited reporting periods and may be revised. Property prices, rents, yields, taxes, and regulations can change. Verify current figures and seek independent professional advice before investing.